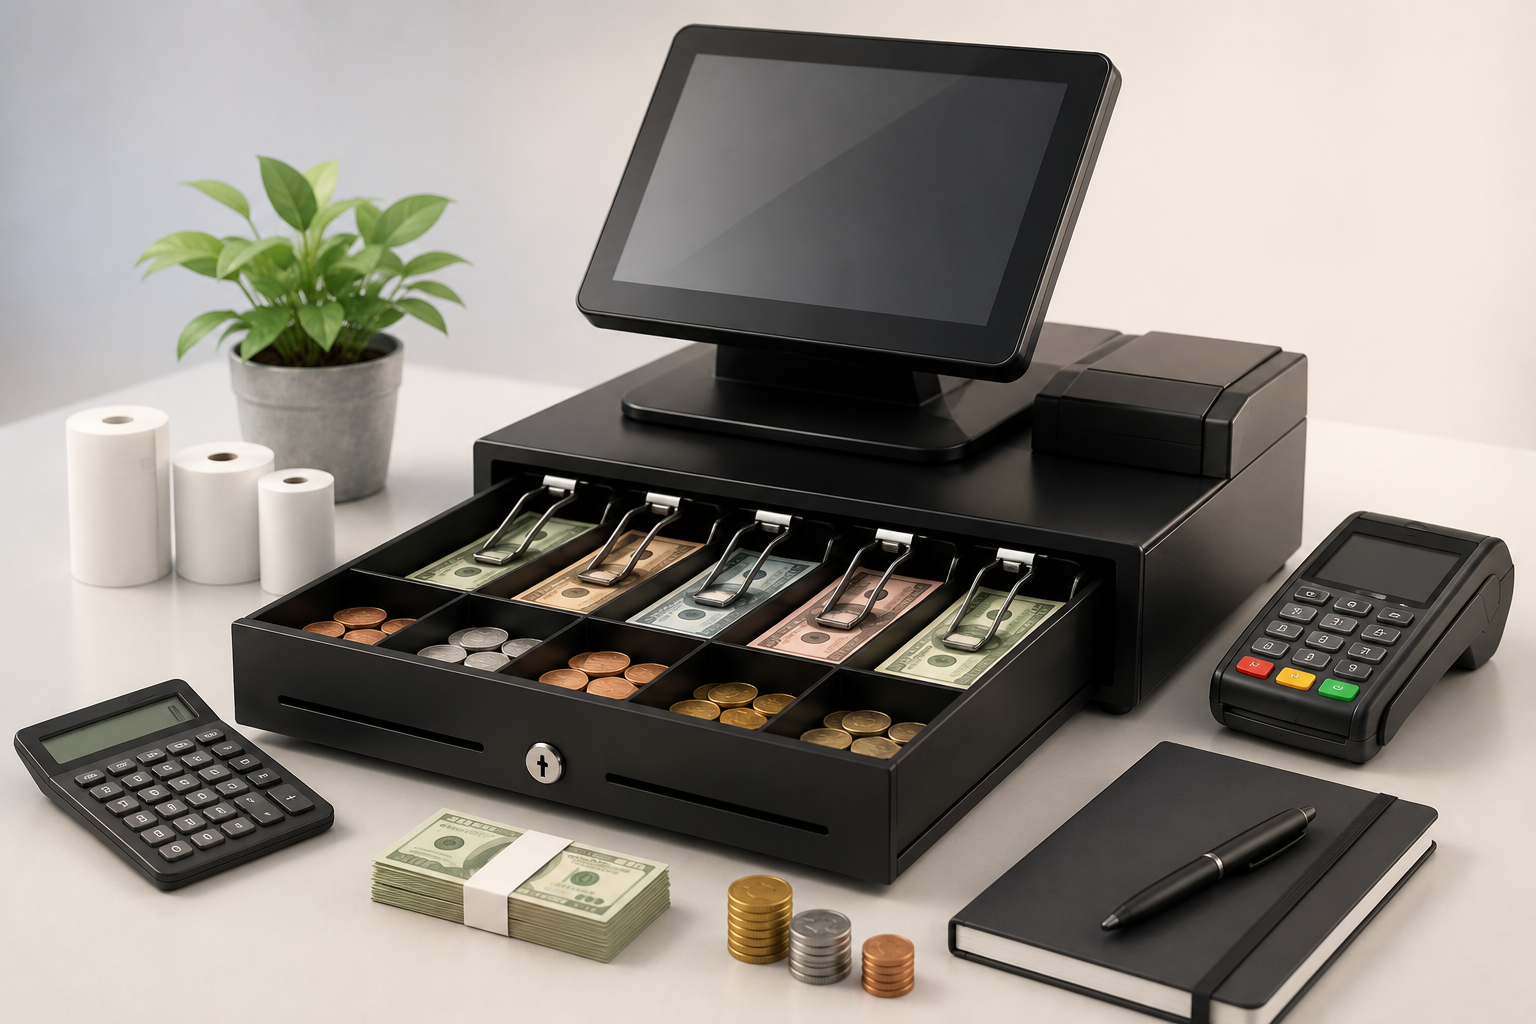
締め作業で現金が不足した——何が起きた?POSシフト照合で原因を特定する
現金差異はレジ担当者を責めるだけでは解決しません。開始金、現金売上、返金、支出、入金、チップ、ドロア開閉、引継ぎ、締め数を結びつけます。
締め作業で現金が不足した——何が起きた?POSシフト照合で原因を特定する
現金差異はレジ担当者を責めるだけでは解決しません。開始金、現金売上、返金、支出、入金、チップ、ドロア開閉、引継ぎ、締め数を結びつけます。
予想現金はすべての動きから計算する
Cash reconciliation should begin with expected cash, calculated from opening float, cash sales, cash refunds, payouts, drops, added change, tips, deposits, and corrections.
Every cash movement must be recorded in the POS or the closing difference becomes difficult to explain.
実際の締め作業を考えます。Cash reconciliation should begin with expected cash, calculated from opening float, cash sales, cash refunds, payouts, drops, added change, tips, deposits, and corrections. Assign one cashier per drawer where possible, or record every user session, ownership change, and handover count. At handover, the outgoing cashier should stop activity, finish pending transactions, count, and transfer responsibility through a documented process. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Overages can also reveal a process failure such as an unrecorded sale or incomplete customer refund. Shortages may come from wrong change, wrong tender, unrecorded expenses, duplicate payouts, forgotten drops, counterfeit cash, or theft. Every cash movement must be recorded in the POS or the closing difference becomes difficult to explain. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。No-sale opens, cash refunds, payouts, and manual corrections need reasons and, for high-risk events, approval or evidence. Strong reconciliation replaces suspicion with evidence and turns each difference into a process improvement. Investigations should compare timeline, transactions, drawer openings, refunds, payouts, voids, user changes, and handovers. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
一つのドロアには明確な責任者が必要
Shared drawers weaken accountability because several users can sell, refund, remove cash, or open the drawer.
Assign one cashier per drawer where possible, or record every user session, ownership change, and handover count.
実際の締め作業を考えます。Assign one cashier per drawer where possible, or record every user session, ownership change, and handover count. Blind counts reduce bias because employees enter the physical amount before seeing the expected balance. Shared drawers weaken accountability because several users can sell, refund, remove cash, or open the drawer. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Strong reconciliation replaces suspicion with evidence and turns each difference into a process improvement. Track frequency, average difference, repeated users, drawers, branches, times, no-sale opens, refund patterns, and delayed closings. Track frequency, average difference, repeated users, drawers, branches, times, no-sale opens, refund patterns, and delayed closings. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
No-sale、返金、支出には理由が必要
No-sale opens, cash refunds, payouts, and manual corrections need reasons and, for high-risk events, approval or evidence.
At handover, the outgoing cashier should stop activity, finish pending transactions, count, and transfer responsibility through a documented process.
実際の締め作業を考えます。Every cash movement must be recorded in the POS or the closing difference becomes difficult to explain. Overages can also reveal a process failure such as an unrecorded sale or incomplete customer refund. Cash reconciliation should begin with expected cash, calculated from opening float, cash sales, cash refunds, payouts, drops, added change, tips, deposits, and corrections. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Shortages may come from wrong change, wrong tender, unrecorded expenses, duplicate payouts, forgotten drops, counterfeit cash, or theft. Shared drawers weaken accountability because several users can sell, refund, remove cash, or open the drawer. Blind counts reduce bias because employees enter the physical amount before seeing the expected balance. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Investigations should compare timeline, transactions, drawer openings, refunds, payouts, voids, user changes, and handovers. Cash reconciliation should begin with expected cash, calculated from opening float, cash sales, cash refunds, payouts, drops, added change, tips, deposits, and corrections. Overages can also reveal a process failure such as an unrecorded sale or incomplete customer refund. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Assign one cashier per drawer where possible, or record every user session, ownership change, and handover count. Blind counts reduce bias because employees enter the physical amount before seeing the expected balance. Shared drawers weaken accountability because several users can sell, refund, remove cash, or open the drawer. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。At handover, the outgoing cashier should stop activity, finish pending transactions, count, and transfer responsibility through a documented process. No-sale opens, cash refunds, payouts, and manual corrections need reasons and, for high-risk events, approval or evidence. No-sale opens, cash refunds, payouts, and manual corrections need reasons and, for high-risk events, approval or evidence. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
引継ぎで証拠を残す
Blind counts reduce bias because employees enter the physical amount before seeing the expected balance.
Shortages may come from wrong change, wrong tender, unrecorded expenses, duplicate payouts, forgotten drops, counterfeit cash, or theft.
実際の締め作業を考えます。No-sale opens, cash refunds, payouts, and manual corrections need reasons and, for high-risk events, approval or evidence. Strong reconciliation replaces suspicion with evidence and turns each difference into a process improvement. Investigations should compare timeline, transactions, drawer openings, refunds, payouts, voids, user changes, and handovers. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Cash reconciliation should begin with expected cash, calculated from opening float, cash sales, cash refunds, payouts, drops, added change, tips, deposits, and corrections. Assign one cashier per drawer where possible, or record every user session, ownership change, and handover count. At handover, the outgoing cashier should stop activity, finish pending transactions, count, and transfer responsibility through a documented process. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
差異は調査する
Overages can also reveal a process failure such as an unrecorded sale or incomplete customer refund.
Investigations should compare timeline, transactions, drawer openings, refunds, payouts, voids, user changes, and handovers.
実際の締め作業を考えます。Shared drawers weaken accountability because several users can sell, refund, remove cash, or open the drawer. Every cash movement must be recorded in the POS or the closing difference becomes difficult to explain. Shortages may come from wrong change, wrong tender, unrecorded expenses, duplicate payouts, forgotten drops, counterfeit cash, or theft. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Blind counts reduce bias because employees enter the physical amount before seeing the expected balance. Investigations should compare timeline, transactions, drawer openings, refunds, payouts, voids, user changes, and handovers. Strong reconciliation replaces suspicion with evidence and turns each difference into a process improvement. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Track frequency, average difference, repeated users, drawers, branches, times, no-sale opens, refund patterns, and delayed closings. At handover, the outgoing cashier should stop activity, finish pending transactions, count, and transfer responsibility through a documented process. Assign one cashier per drawer where possible, or record every user session, ownership change, and handover count. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Shared drawers weaken accountability because several users can sell, refund, remove cash, or open the drawer. Every cash movement must be recorded in the POS or the closing difference becomes difficult to explain. Shortages may come from wrong change, wrong tender, unrecorded expenses, duplicate payouts, forgotten drops, counterfeit cash, or theft. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
傾向を業務改善に使う
Track frequency, average difference, repeated users, drawers, branches, times, no-sale opens, refund patterns, and delayed closings.
Strong reconciliation replaces suspicion with evidence and turns each difference into a process improvement.
実際の締め作業を考えます。At handover, the outgoing cashier should stop activity, finish pending transactions, count, and transfer responsibility through a documented process. No-sale opens, cash refunds, payouts, and manual corrections need reasons and, for high-risk events, approval or evidence. No-sale opens, cash refunds, payouts, and manual corrections need reasons and, for high-risk events, approval or evidence. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
実際の締め作業を考えます。Every cash movement must be recorded in the POS or the closing difference becomes difficult to explain. Overages can also reveal a process failure such as an unrecorded sale or incomplete customer refund. Cash reconciliation should begin with expected cash, calculated from opening float, cash sales, cash refunds, payouts, drops, added change, tips, deposits, and corrections. 現金返金、支出、ドロップ、No-sale開閉、引継ぎ、ブラインドカウント、再集計をテストします。
Keep reading
POSは次の一手を提案できる。でも決定まで任せるべきか?小売AI実践ガイド
AIはダッシュボードから日常業務へ進み、需要予測、補充提案、異常検知、顧客離脱予測、業績要約を行います。価値、限界、人の承認を解説します。
記事を読む
顧客はデポジットを払ったが販売は未完了:POSで予約販売、取り置き、分割支払を管理する
デポジット、予約販売、取り置き、特注は需要と資金繰りを支えますが、在庫、顧客残高、期限、返金、会計の連携が必要です。
記事を読む
倉庫は満杯なのに売れ筋がない:POSで補充と滞留在庫を改善する方法
倉庫が満杯でも在庫が健全とは限りません。販売速度、リードタイム、季節性、発注点、仕入先実績を活用します。
記事を読む