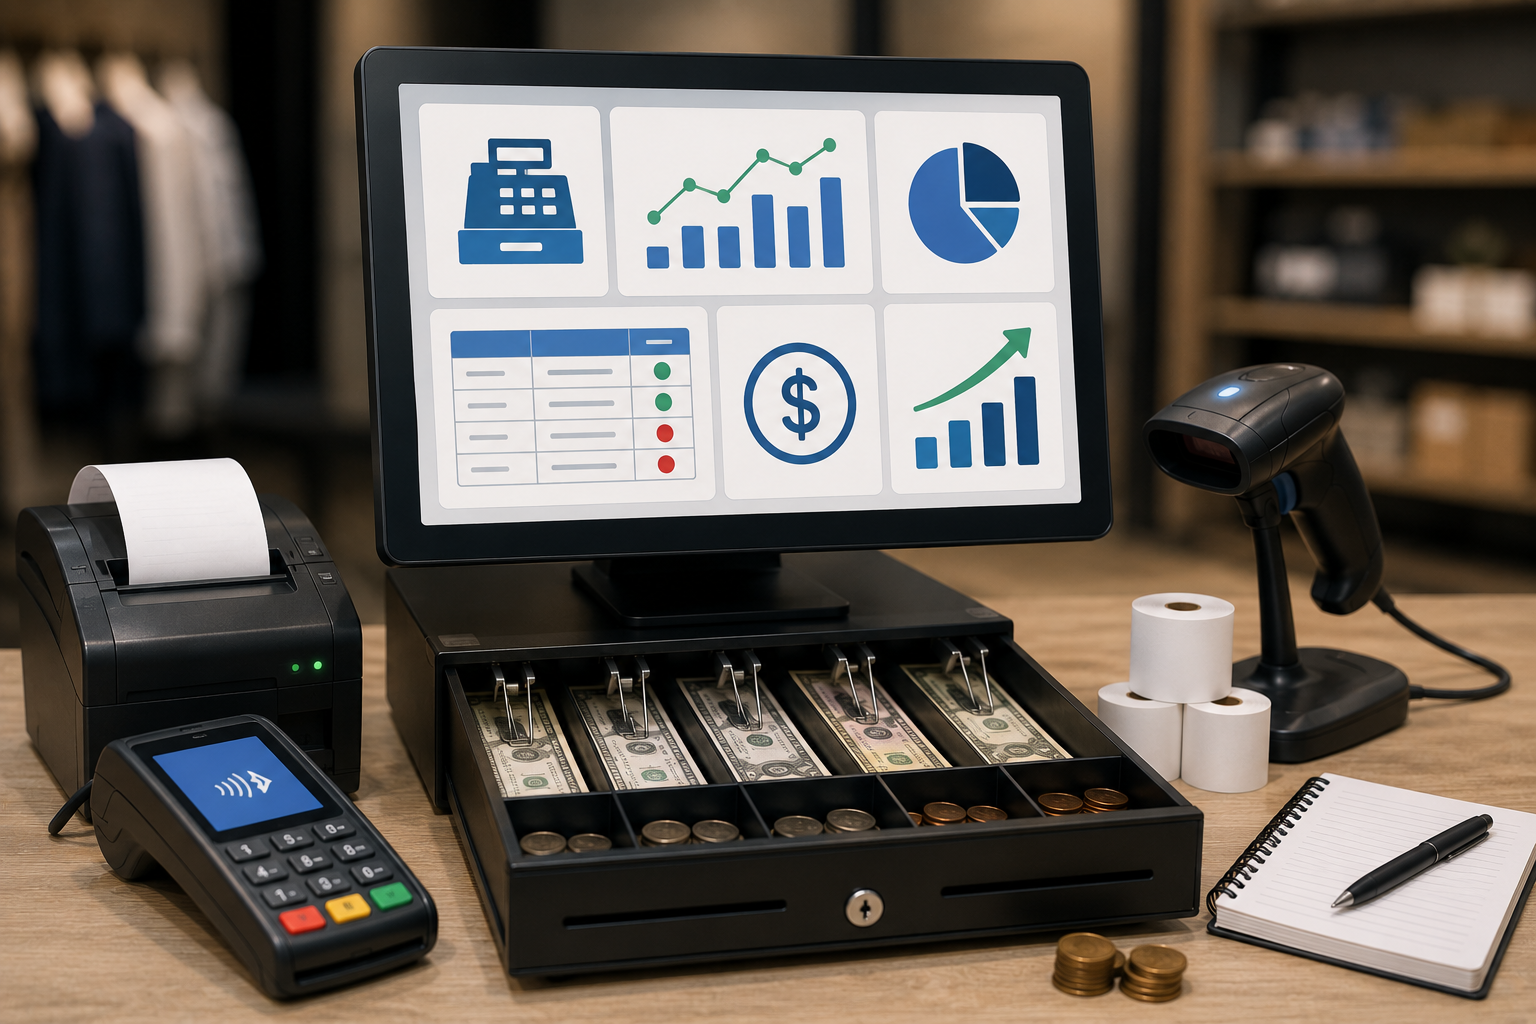
Kasir kurang—ke mana uangnya? Panduan POS untuk rekonsiliasi laci kas dan pembayaran
Selisih saat tutup kas tidak otomatis berarti pencurian. Pelajari sesi kasir, modal awal, uang masuk-keluar, refund, settlement kartu, dan akuntabilitas.
Kasir kurang—ke mana uangnya? Panduan POS untuk rekonsiliasi laci kas dan pembayaran
Selisih saat tutup kas tidak otomatis berarti pencurian. Pelajari sesi kasir, modal awal, uang masuk-keluar, refund, settlement kartu, dan akuntabilitas.
Selisih kas adalah gejala, bukan vonis
A cash shortage can come from theft, wrong change, an unrecorded sale, an incorrect refund tender, an undocumented expense, a wrong opening float, or a counting error.
The variance is a signal for investigation, not automatic proof of misconduct.
Sebagai contoh, A cash shortage can come from theft, wrong change, an unrecorded sale, an incorrect refund tender, an undocumented expense, a wrong opening float, or a counting error. Shared drawers and unclear shift handovers weaken accountability and make the final difference difficult to explain. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, Fees, refunds, chargebacks, tips, batch cut-offs, holidays, and reserves can make the bank deposit differ from POS sales. Each register session needs location, device, employee, opening time, starting float, closing time, expected cash, counted cash, and variance. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, Each register session needs location, device, employee, opening time, starting float, closing time, expected cash, counted cash, and variance. The variance is a signal for investigation, not automatic proof of misconduct. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Setiap laci perlu sesi yang jelas
Each register session needs location, device, employee, opening time, starting float, closing time, expected cash, counted cash, and variance.
Shared drawers and unclear shift handovers weaken accountability and make the final difference difficult to explain.
Sebagai contoh, Shared drawers and unclear shift handovers weaken accountability and make the final difference difficult to explain. Card authorization happens at checkout, while settlement and bank funding can arrive later. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, A trusted close records movements, closes batches, counts denominations, compares expected with actual, documents variance, and secures the deposit. Every paid-in and paid-out movement needs amount, reason, time, user, approval, and supporting evidence. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, Every paid-in and paid-out movement needs amount, reason, time, user, approval, and supporting evidence. Expected cash equals opening float plus cash sales and additions, minus refunds and approved removals. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Kas yang diharapkan hanya benar jika semua pergerakan dicatat
Expected cash equals opening float plus cash sales and additions, minus refunds and approved removals.
Every paid-in and paid-out movement needs amount, reason, time, user, approval, and supporting evidence.
Sebagai contoh, The variance is a signal for investigation, not automatic proof of misconduct. Repeated shortages or overages by shift, drawer, employee, payment type, or transaction pattern need deeper analysis. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, Repeated shortages or overages by shift, drawer, employee, payment type, or transaction pattern need deeper analysis. Fees, refunds, chargebacks, tips, batch cut-offs, holidays, and reserves can make the bank deposit differ from POS sales. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, Shared drawers and unclear shift handovers weaken accountability and make the final difference difficult to explain. Card authorization happens at checkout, while settlement and bank funding can arrive later. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Penjualan kartu dan dana bank memiliki waktu berbeda
Card authorization happens at checkout, while settlement and bank funding can arrive later.
Fees, refunds, chargebacks, tips, batch cut-offs, holidays, and reserves can make the bank deposit differ from POS sales.
Sebagai contoh, Expected cash equals opening float plus cash sales and additions, minus refunds and approved removals. A strong POS connects sessions, users, cash movements, refunds, payment types, settlements, branches, and audit history. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, A strong POS connects sessions, users, cash movements, refunds, payment types, settlements, branches, and audit history. A trusted close records movements, closes batches, counts denominations, compares expected with actual, documents variance, and secures the deposit. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Selidiki pola, bukan menyalahkan kasir terakhir
Repeated shortages or overages by shift, drawer, employee, payment type, or transaction pattern need deeper analysis.
Audit voids, refunds, no-sale openings, manual discounts, cancelled payments, and handovers in a fair and proportionate way.
Sebagai contoh, Each register session needs location, device, employee, opening time, starting float, closing time, expected cash, counted cash, and variance. The variance is a signal for investigation, not automatic proof of misconduct. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, Card authorization happens at checkout, while settlement and bank funding can arrive later. Audit voids, refunds, no-sale openings, manual discounts, cancelled payments, and handovers in a fair and proportionate way. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, Audit voids, refunds, no-sale openings, manual discounts, cancelled payments, and handovers in a fair and proportionate way. A cash shortage can come from theft, wrong change, an unrecorded sale, an incorrect refund tender, an undocumented expense, a wrong opening float, or a counting error. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, The variance is a signal for investigation, not automatic proof of misconduct. Repeated shortages or overages by shift, drawer, employee, payment type, or transaction pattern need deeper analysis. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, Expected cash equals opening float plus cash sales and additions, minus refunds and approved removals. A strong POS connects sessions, users, cash movements, refunds, payment types, settlements, branches, and audit history. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Bangun penutupan yang dipercaya keuangan
A trusted close records movements, closes batches, counts denominations, compares expected with actual, documents variance, and secures the deposit.
A strong POS connects sessions, users, cash movements, refunds, payment types, settlements, branches, and audit history.
Sebagai contoh, Every paid-in and paid-out movement needs amount, reason, time, user, approval, and supporting evidence. Expected cash equals opening float plus cash sales and additions, minus refunds and approved removals. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Sebagai contoh, A cash shortage can come from theft, wrong change, an unrecorded sale, an incorrect refund tender, an undocumented expense, a wrong opening float, or a counting error. Shared drawers and unclear shift handovers weaken accountability and make the final difference difficult to explain. Koreksi harus memperbaiki proses dan menyimpan jejak audit, bukan hanya mengubah saldo.
Keep reading
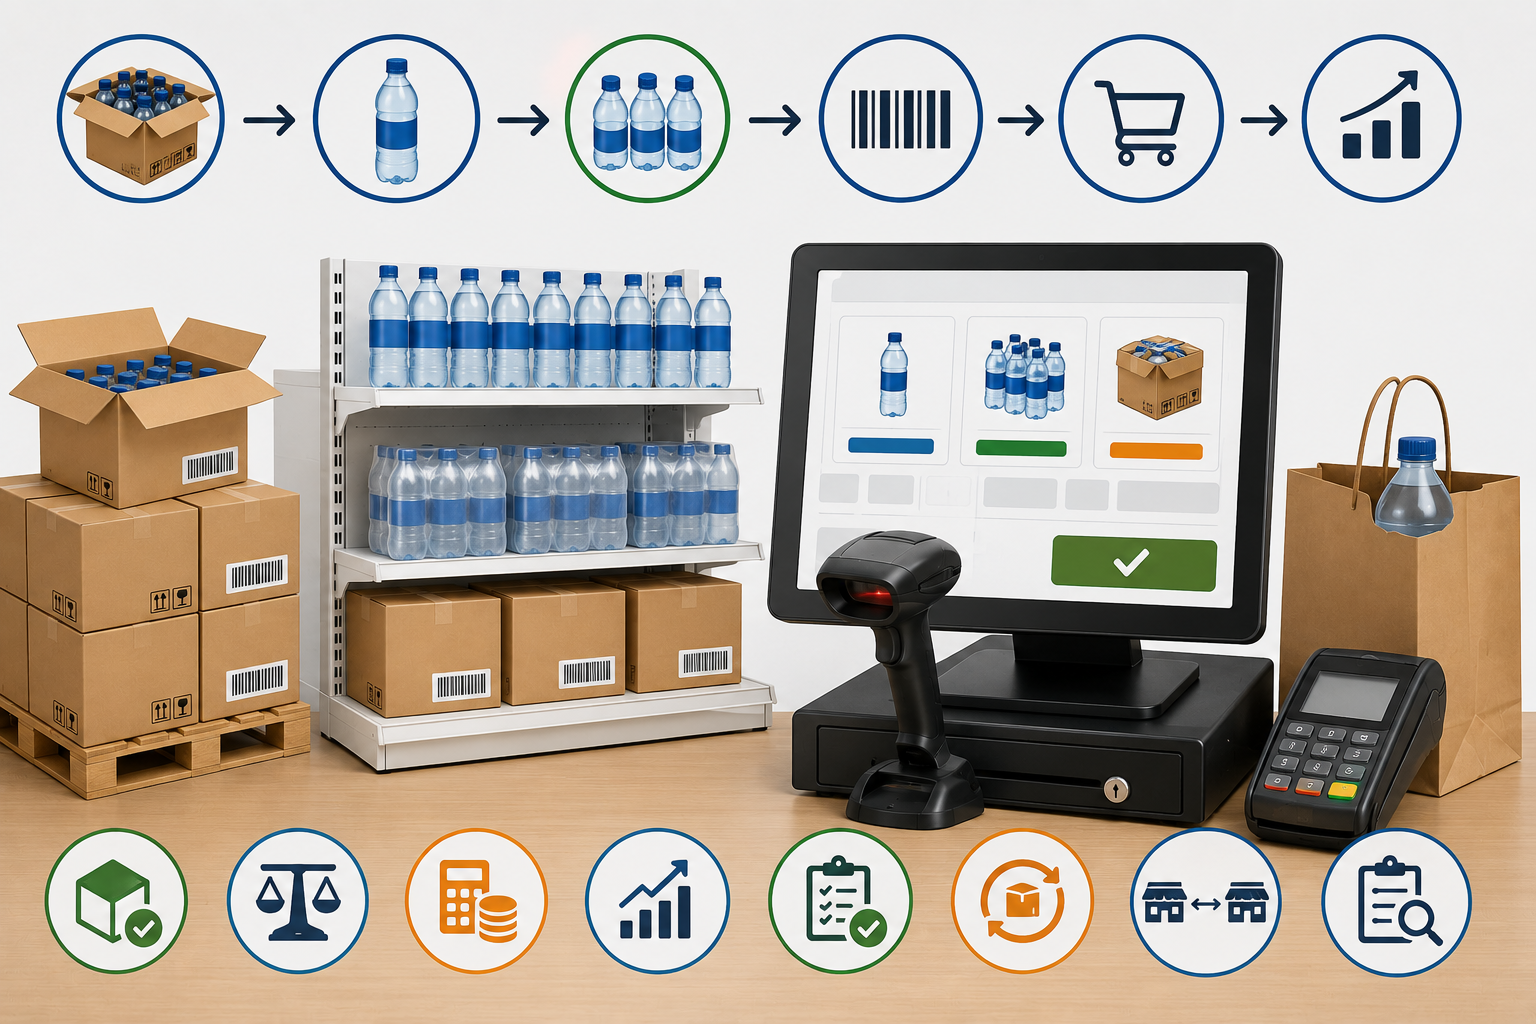
Membeli satu karton isi 24, menjual satu botol: satuan ukur POS mencegah kesalahan stok
Retail membeli per karton, menerima per pack, dan menjual per unit. Pelajari konversi, barcode, biaya per unit, hitung stok, retur, dan pembelian.
Baca artikel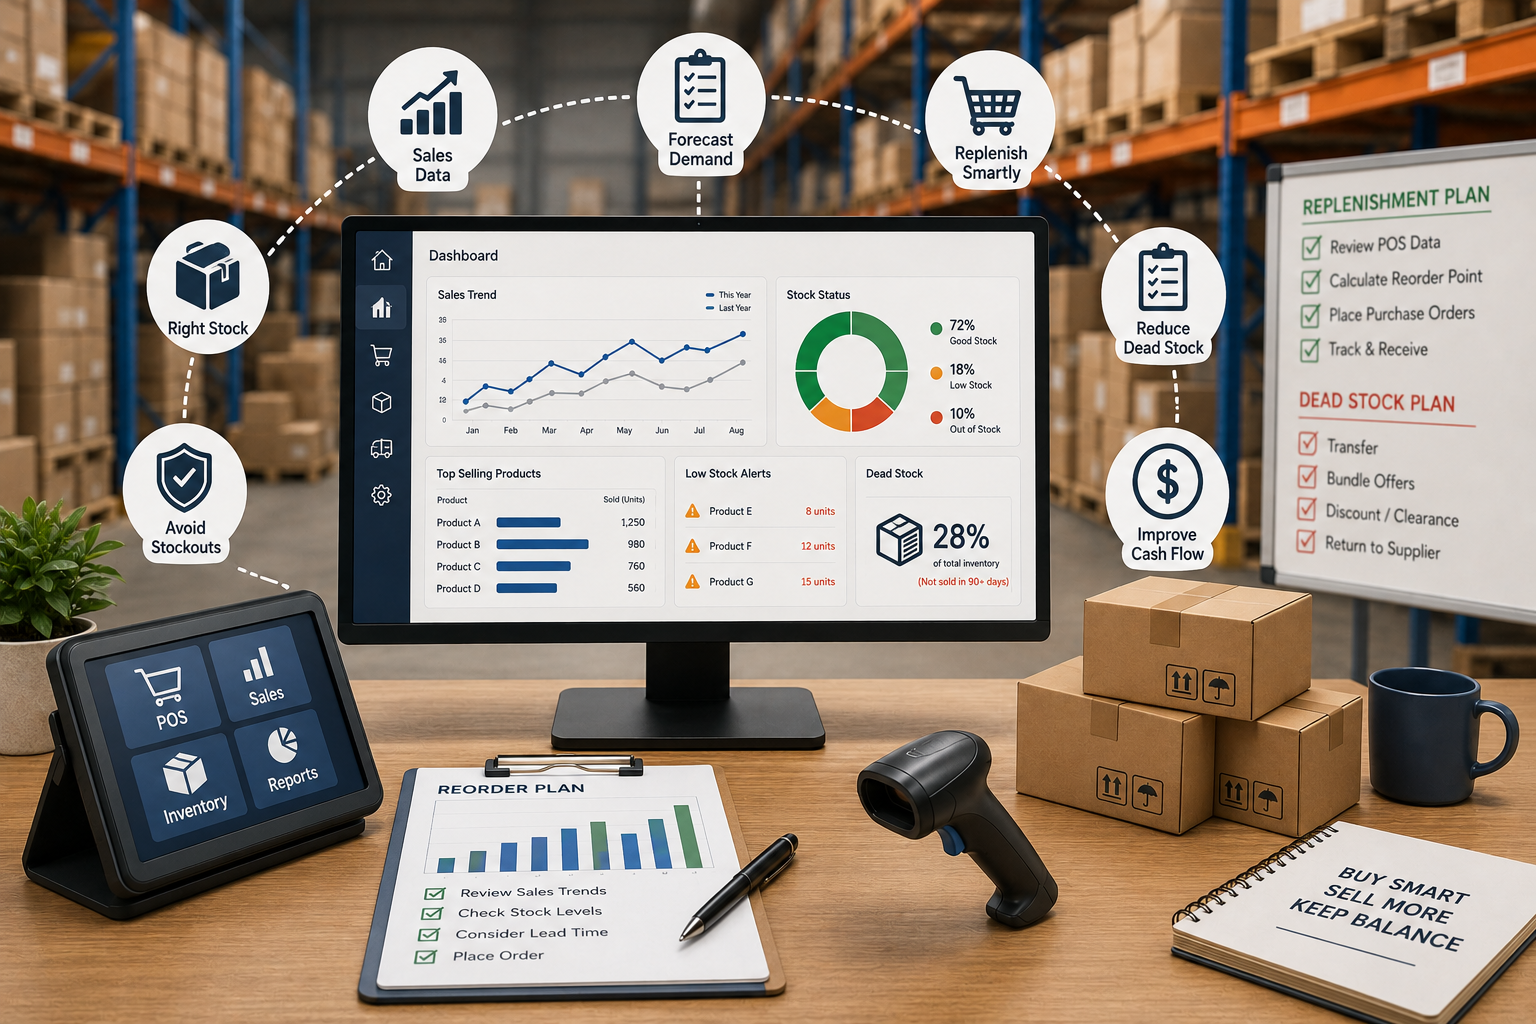
Gudang penuh tetapi produk terlaris habis: POS memperbaiki replenishment dan dead stock
Gudang penuh bukan berarti stok sehat. Gunakan sales velocity, lead time, musim, reorder point, dan kinerja pemasok.
Baca artikel
Gift card dijual berbulan-bulan lalu—mengapa masih menjadi kewajiban? Mengelola stored value di POS
Gift card membawa kas lebih awal, tetapi menciptakan saldo, kewajiban penukaran, fraud, masa berlaku, split payment, refund, dan pekerjaan akuntansi.
Baca artikel